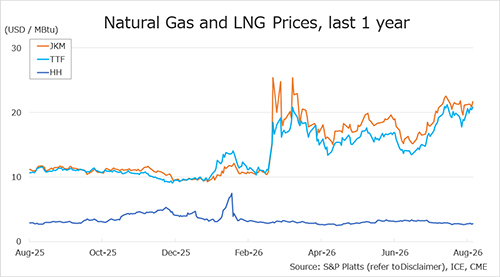
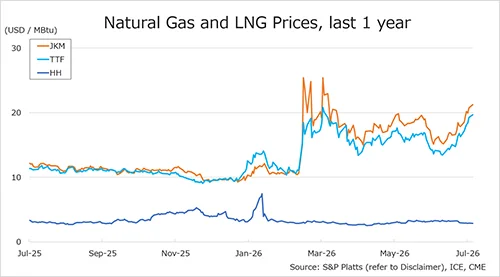
Natural gas prices rose sharply in Asia and Europe last week as geopolitical tensions and supply concerns intensified. JKM reached its highest level in about two and a half years, while Henry Hub weakened on robust U.S. production and ample inventories.
Asia – JKM
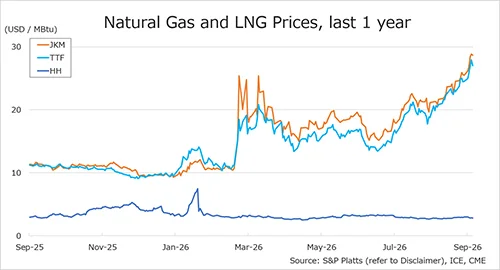
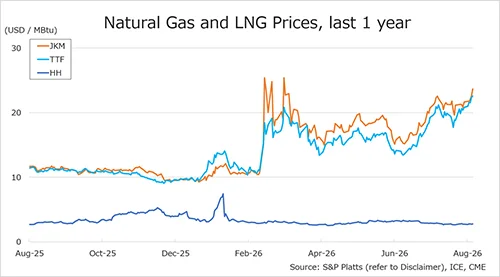
The Northeast Asian assessed spot LNG price JKM for last week (7–11 September, October delivery) rose to mid-USD 28s/MBtu on 11 September from mid-USD 25s/MBtu the previous weekend (4 September).
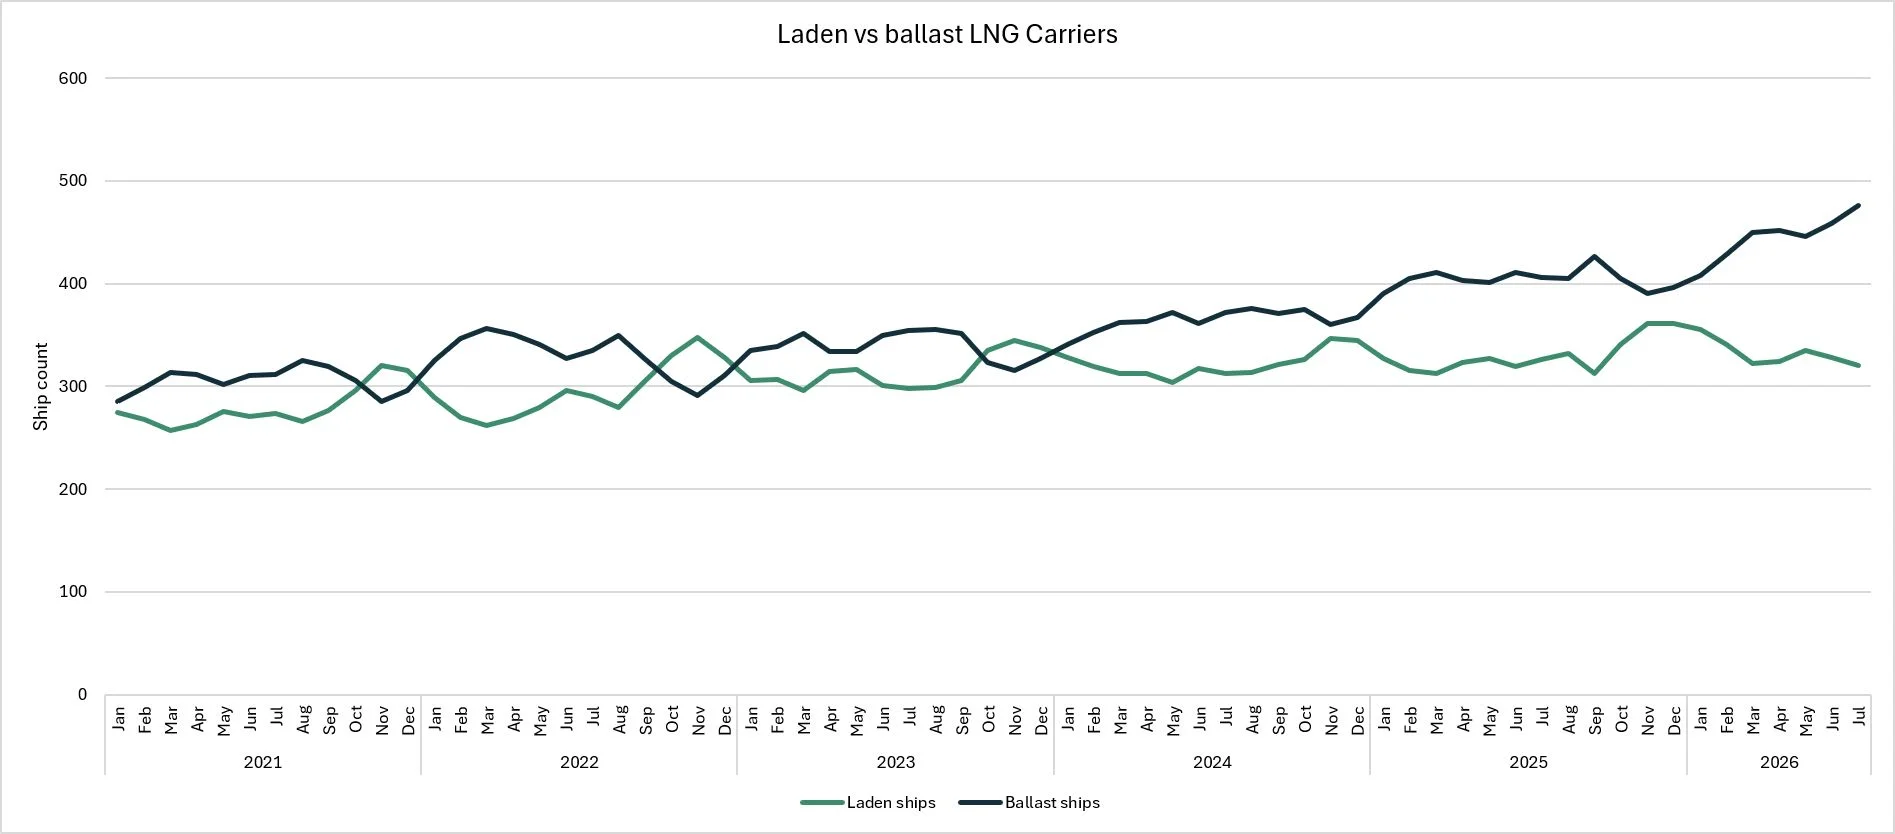
At the beginning of the week, JKM rose on rising geopolitical risk premiums following escalating tensions in the Middle East and concerns over supply availability as the arbitrage for U.S. LNG cargoes to Asia remained closed.
JKM continued to climb during the week amid growing military tensions between the U.S. and Iran and strong spot LNG procurement by South Asian buyers, reaching high-USD 28s/MBtu on 10 September, the highest level in about two and a half years.
On 11 September, JKM edged lower on reports that Iran had begun talks with neighboring countries, raising expectations of easing geopolitical tensions. However, JKM remained at a high level in the mid-USD 28s/MBtu.
METI announced on 9 September that Japan’s LNG inventories for power generation as of 6 September stood at 2.43 million tonnes, up 0.06 million tonnes from the previous week.
Europe – TTF
The European gas price TTF (October delivery) for last week (7–11 September) rose to USD 27.0/MBtu on 11 September from USD 24.5/MBtu the previous weekend (4 September).
At the start of the week, TTF increased on supply concerns following unplanned maintenance at Norway’s Asgard and Troll gas fields and the Kollsnes processing plant, as well as the shutdown of the Interconnector UK (IUK) pipeline linking the UK and Belgium.
TTF continued to rise during the week amid growing concerns over supply risks, following reports of exchanges of attacks between the U.S. and Iran, Houthi attacks on energy facilities in Saudi Arabia, and attacks on Russian fuel and energy infrastructure.
Concerns over slower gas storage injections in Europe and lower wind power generation also supported prices, with the TTF contract trading above USD 28/MBtu on 10 September.
However, profit-taking after the recent rally pushed prices down to USD 27.0/MBtu on 11 September.
According to AGSI+, EU-wide underground gas storage was 67.8% on 11 September, up from 66.4% the previous weekend, down 15.7% from the same period last year, and down 19.6% from the five-year average.
United States – Henry Hub
The U.S. gas price HH (October delivery) for last week (7–11 September) fell to USD 2.8/MBtu on 11 September from USD 3.0/MBtu the previous weekend (4 September).
From the beginning of the week, robust dry gas production and ample inventories weighed on prices, while forecasts for cooler temperatures reduced demand expectations, pushing HH down to USD 2.8/MBtu on 9 September.
It later recovered slightly but remained largely unchanged, trading in the low-USD 2.8/MBtu range.
The EIA Weekly Natural Gas Storage Report released on 10 September showed U.S. natural gas inventories as of 4 September at 3,254 Bcf, up 40 Bcf from the previous week, down 2.4% from the same period last year, and 4.8% above the five-year average.
Source: JOGMEC
Updated: 14 September 2026