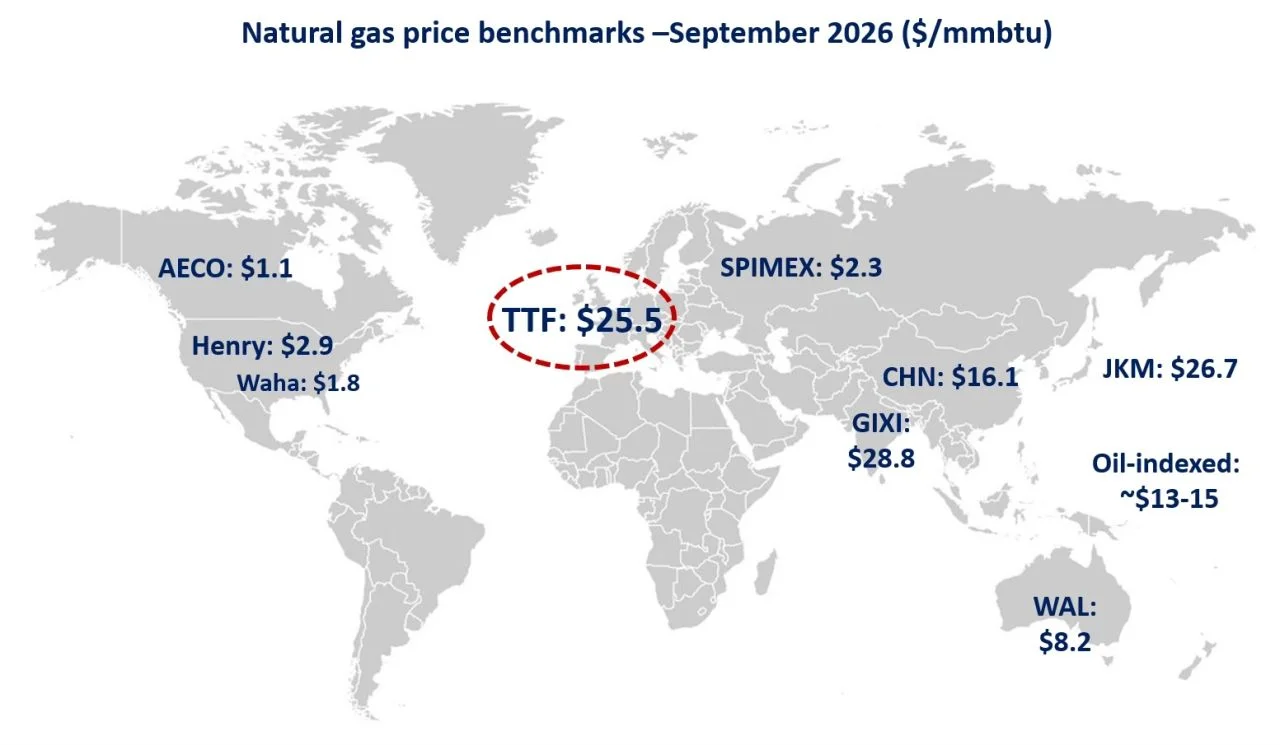
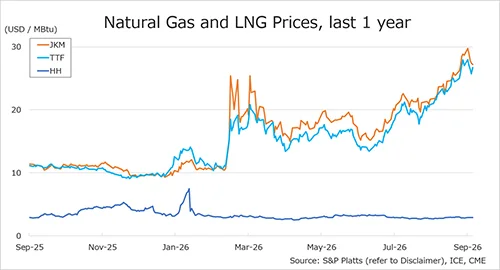
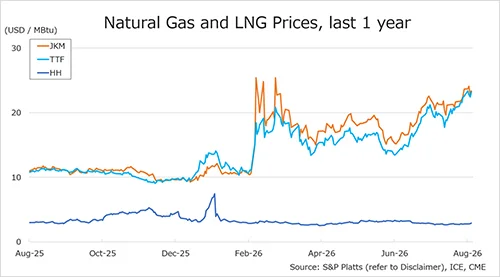
Natural gas prices showed mixed movements last week as Middle East developments and changing supply expectations drove volatility. JKM and Henry Hub declined, while TTF rose as European markets refocused on winter supply risks and relatively low storage levels.
Asia – JKM
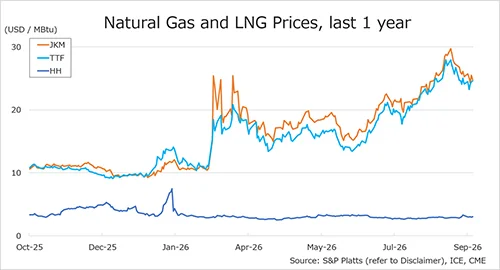
The Northeast Asian assessed spot LNG price JKM for last week (28 September–2 October, November delivery) fell to high-USD 24s/MBtu on 2 October from low-USD 25s/MBtu the previous weekend (25 September).
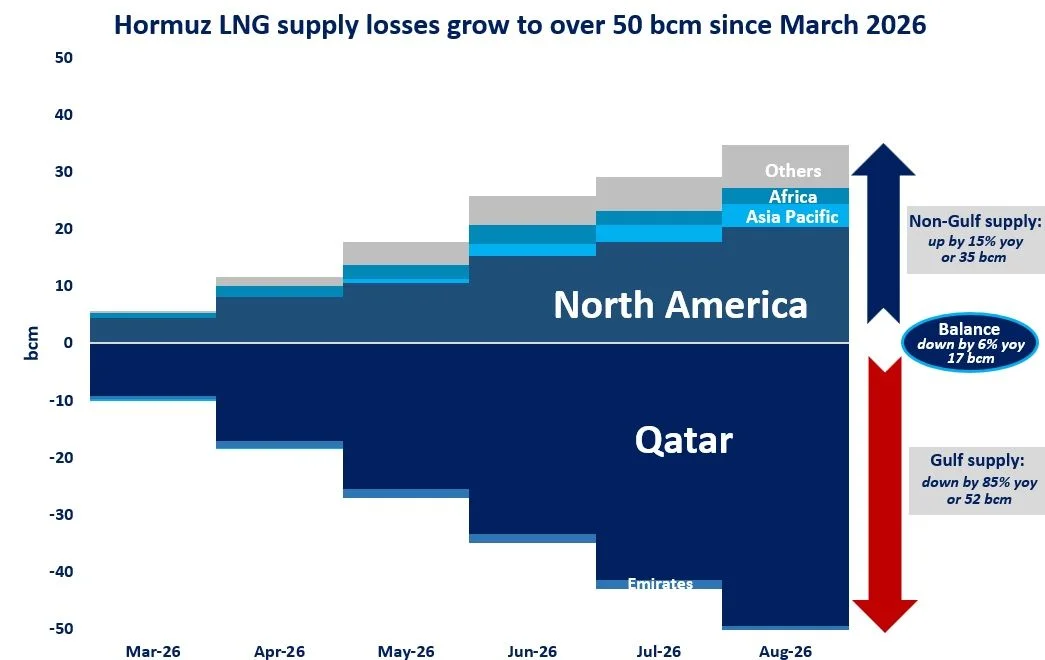
At the beginning of the week, JKM rose to high-USD 25s/MBtu, supported by concerns over tight near-term market fundamentals and potential disruptions to LNG shipments through the Strait of Hormuz.
However, it later fell to the low-USD 24s/MBtu range by 30 September, as expectations for easing tensions in the Middle East following progress in U.S.-Iran ceasefire talks, together with weak Asian demand led by China and South Korea, weighed on the market.
JKM then rebounded to mid-USD 25s/MBtu on 1 October as concerns resurfaced over supply risks associated with the Strait of Hormuz and the tight availability of November-loading cargoes.
Nevertheless, JKM declined again to high-USD 24s/MBtu on 2 October amid subdued buying interest in East Asia and expectations of a mild winter.
METI announced on 30 September that Japan’s LNG inventories for power generation as of 27 September stood at 2.41 million tonnes, down 0.11 million tonnes from the previous week.
Europe – TTF
The European gas price TTF for last week (28 September–2 October) rose to USD 24.6/MBtu on 2 October (November delivery) from USD 24.1/MBtu the previous weekend (25 September, October delivery).
At the beginning of the week, TTF rose to USD 24.5/MBtu, supported by concerns over supply disruptions related to the Middle East situation and Europe’s relatively low gas storage levels.
However, it plunged to USD 23.2/MBtu on 29 September amid expectations of progress in U.S.-Iran ceasefire talks, increased gas supply from Norway and weak LNG demand from China.
Thereafter, as the front-month contract rolled over to November and market participants refocused on winter supply risks and European gas storage levels remaining well below the previous year’s level, TTF continued to rise, reaching USD 24.6/MBtu on 2 October.
According to AGSI+, EU-wide underground gas storage was 72.2% on 2 October, up from 70.6% the previous weekend, down 13.3% from the same period last year and down 17.5% from the five-year average.
United States – Henry Hub
The U.S. gas price HH for last week (28 September–2 October, November delivery) fell to USD 3.0/MBtu on 2 October from USD 3.2/MBtu the previous weekend (25 September, October delivery).
At the beginning of the week, HH fell to USD 3.0/MBtu on 28 September as warmer temperature forecasts across the Midwest and Southeast dampened expectations for heating demand.
Thereafter, while expectations for the upcoming winter heating season and stronger LNG demand from Europe provided some support, HH continued to trade around USD 3.0/MBtu amid continued warm weather forecasts and strong gas production.
The EIA Weekly Natural Gas Storage Report released on 1 October showed U.S. natural gas inventories as of 25 September at 3,415 Bcf, up 64 Bcf from the previous week, down 3.9% from the same period last year and 2.4% above the five-year average.
Source: JOGMEC
Updated: 5 October 2026